
When buying or selling Australian property, one of the most important regulations to understand is the foreign resident capital gains withholding (FRCGW) regime.
This is not an obscure piece of tax legislation; it is a fundamental part of the property transaction process in Australia. In simple terms, this rule requires a buyer to withhold a portion of the purchase price from a seller who is a foreign resident for tax purposes and pay it directly to the Australian Taxation Office (ATO). It's important to understand this is not a new tax, but a prepayment of the seller's anticipated capital gains tax liability, ensuring this obligation is addressed at the point of sale.
A clear understanding of this rule is essential for anyone involved in Australian property transactions to ensure compliance and a smooth settlement.
Understanding the Foreign Resident Withholding Framework
The FRCGW regime can be seen as a mechanism to safeguard Australia's tax revenue system. It was established by the Australian government to address a specific challenge: foreign residents selling Australian assets and leaving the country without fulfilling their capital gains tax obligations.
At its core, the rule places a clear legal duty on the purchaser of certain Australian assets. If you purchase a property from an individual or entity deemed a foreign resident for tax purposes, you are required to withhold a percentage of the sale price and remit it to the ATO. This process ensures a portion of the potential tax is secured at the time of the transaction.
Core Principles of the Withholding Rule
For both purchasers and sellers, grasping a few key principles can make the process more manageable. It is helpful to view this not as a penalty, but as a standard component of settlement that requires careful planning.
The main concepts to keep in mind are:
- It’s a Prepayment, Not a Final Tax: The amount withheld is an instalment towards the seller’s final tax liability. The foreign resident seller is still required to lodge an Australian tax return to declare their capital gain or loss. At that time, they can claim a credit for the amount that was withheld.
- The Onus is on the Purchaser: This is a critical point. Australian law places the responsibility to withhold and remit the funds squarely on the buyer. Failure to comply could result in the purchaser being liable for the entire withholding amount, in addition to potential penalties from the ATO.
- Residency Status is Key: The entire process depends on the seller's residency status for tax purposes. This must be determined before the day of settlement. We cover some of the nuances of this in our guide on how to buy a home in Australia as a temporary resident.
This withholding mechanism is designed to protect the integrity of our tax system. It helps ensure that the tax base is not diminished by offshore transactions involving Australian assets, creating a more equitable environment for all taxpayers.
This framework underscores the importance of due diligence. For purchasers, it is a compliance task that cannot be overlooked. For sellers, it is a financial reality that directly impacts settlement proceeds. Approaching it with a clear understanding of your obligations is the first step towards a smooth transaction and sound financial stewardship.
How the FRCGW Rules Have Evolved Over Time
To properly understand the foreign resident capital gains withholding rules, it is useful to consider their history. This system is the result of a deliberate, multi-year effort by the Australian government to strengthen the integrity of the tax system.
The origins of FRCGW lie in a long-standing challenge. For years, the Australian Taxation Office (ATO) faced difficulties in collecting capital gains tax from foreign residents who sold Australian property. It was often possible for a vendor to sell an asset, receive the full proceeds, and move overseas without lodging a tax return. This created a revenue gap that required a structural solution.
The Original Framework and Its Purpose
The government's solution was to shift the point of collection. Instead of pursuing the seller for tax after the transaction, the obligation was placed on the buyer to collect it at the point of sale. This led to the creation of the foreign resident capital gains withholding (FRCGW) regime, which commenced on 1 July 2016.
Initially, the rules were targeted at higher-value transactions. The ATO established a withholding rate of 10% for any property sale with a market value over a $2 million threshold. This represented a significant shift in how Australia collected tax from foreign investors, as detailed in early insights into Australia's withholding rate changes. It was a measured first step, designed to capture the largest transactions where the potential tax leakage was greatest.
Broadening the Net Over Time
It soon became apparent that the initial settings were too narrow. With a strong property market, a significant volume of sales was occurring just below the $2 million threshold, meaning a considerable amount of potential tax revenue remained unsecured.
Consequently, just one year later, the government expanded the regime:
- From 1 July 2017, the property value threshold was lowered significantly from $2 million to $750,000.
- Simultaneously, the withholding rate was increased from 10% to 12.5%.
This was a pivotal change. It brought a much larger volume of property sales into the FRCGW net, signalling that compliance was a standard part of business for most transactions involving a foreign resident vendor. It also made understanding structures like a bare trust for property investment even more important for those with complex ownership arrangements.
The evolution of the FRCGW rules demonstrates a clear and consistent policy direction: to close loopholes and ensure the tax system is robust. Each amendment has expanded the scope of the rules, clarifying obligations for all parties.
The Most Recent Changes
The trend towards stricter rules has continued. Recognising that the $750,000 threshold could still be circumvented, the government announced another major adjustment, which took effect from 1 January 2025.
These amendments are the most significant to date. The withholding rate increased again, this time to 15%. However, the most profound change is that the $750,000 property value threshold has been removed entirely.
This means that from 2025 onwards, FRCGW applies to all property sales by foreign residents, regardless of the purchase price. A $400,000 apartment may be treated in the same manner as a $4 million commercial building.
This history shows a steady progression towards comprehensive oversight. For anyone involved in Australian property today, it serves as a reminder that staying informed and seeking grounded advice is not just prudent, but necessary.
Your Obligations as a Buyer or Seller
When navigating a property transaction, understanding your specific role is key to a smooth settlement. The foreign resident capital gains withholding (FRCGW) rules outline distinct responsibilities for purchasers and vendors. Fulfilling these obligations is a legal requirement that protects all parties involved.
As the purchaser, your primary duty is one of due diligence and action. You are legally required to determine the seller’s tax residency status. If the seller is a foreign resident, you must withhold a portion of the purchase price at settlement and remit it directly to the ATO. This is a strict liability obligation. If you fail to do so, the ATO may hold you liable for the entire withholding amount, plus penalties.
For vendors, the main responsibility is to provide clear information regarding your residency status. If you are an Australian resident for tax purposes, you can prevent any withholding by providing the purchaser with a valid ATO Clearance Certificate before settlement. This document provides the buyer with the necessary authority to release the full sale proceeds to you on the day.
This timeline shows how the FRCGW rules have been tightening over the years, with a clear trend towards catching more transactions and demanding stricter compliance.
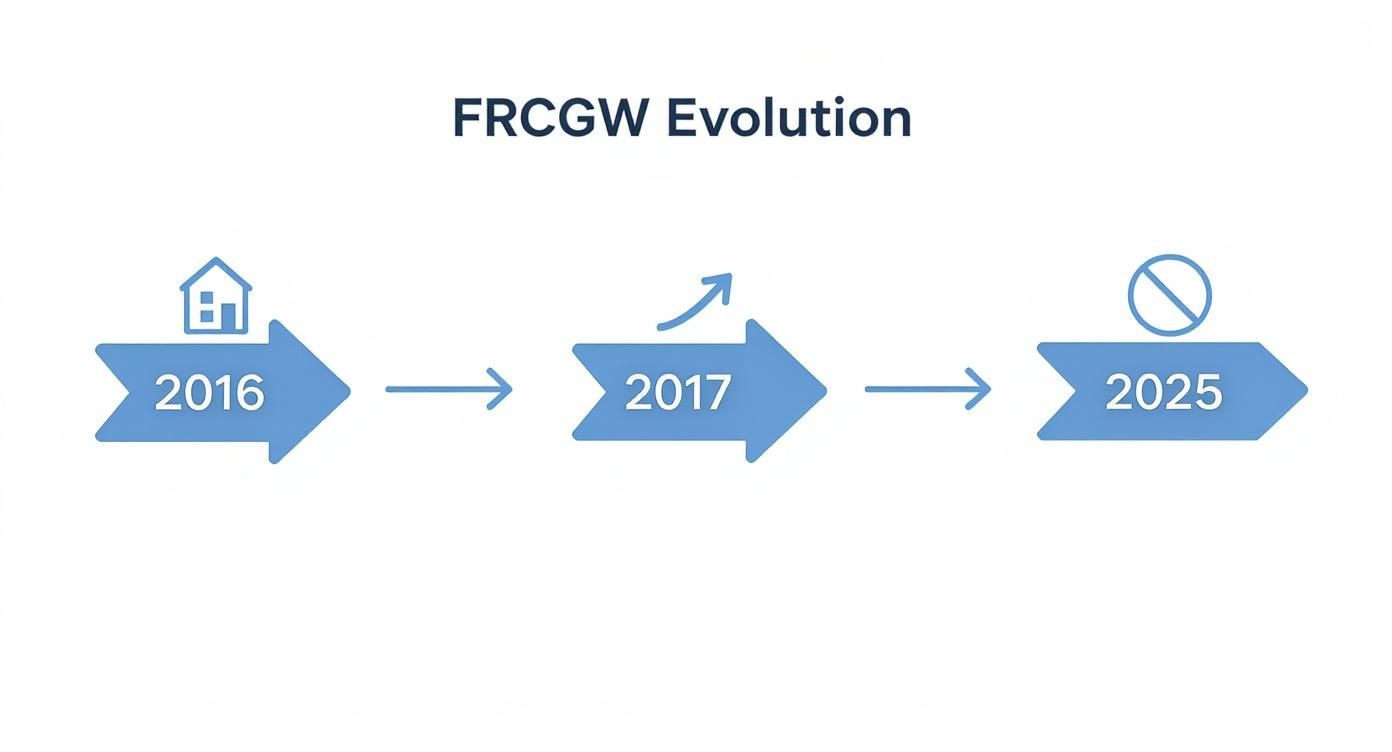
The biggest change is just around the corner: from 2025, the value threshold is being removed, which means these rules will apply to almost every single property sale.
To provide greater clarity, here is a summary of who needs to do what.
FRCGW Obligations At-a-Glance
| Party | Primary Obligation | Key Action | Primary Risk of Non-Compliance |
|---|---|---|---|
| Purchaser (Buyer) | Withhold and remit tax if the vendor is a foreign resident. | Determine vendor's residency; withhold funds at settlement and pay to ATO. | Liability for the unpaid withholding amount plus significant penalties. |
| Vendor (Seller) | Declare residency status accurately. | Provide a valid ATO Clearance Certificate to the purchaser before settlement. | Having 15% of the sale price withheld, impacting cash flow at settlement. |
Ultimately, a clear understanding of these distinct roles enables both sides to prepare adequately and avoid unwelcome complications at a critical stage of the transaction.
A Purchaser's Checklist for Compliance
As a buyer, your duties are centred on a clear, methodical process. This approach will help you navigate settlement with confidence and protect you from financial risk. Here are the steps to follow:
Confirm the Seller’s Residency Status: You must take reasonable steps to determine if the vendor is an Australian or foreign resident for tax purposes. This is typically done by requesting a clearance certificate or relying on their declaration in the sale contract.
Verify the Clearance Certificate: If the vendor provides a certificate, you need to confirm its validity. Ensure the name on the certificate exactly matches the name on the property title and that it is valid for the settlement date.
Withhold if Necessary: If the vendor is a foreign resident, or if they do not provide a valid clearance certificate in time, you are legally obligated to withhold 15% of the purchase price (for contracts from 1 January 2025).
Lodge and Pay: After withholding the funds, you must complete the ATO's Purchaser payment notification form and remit the withheld amount on or before the day of settlement.
The law is unambiguous: the responsibility to withhold the funds and pay them to the ATO rests entirely with the purchaser. This is not a responsibility that can be delegated.
A Vendor's Checklist for a Smooth Sale
As a seller, a proactive stance is the best strategy for a seamless settlement. Your main objective, assuming you are an Australian resident, is to provide the correct documentation to the purchaser so they are not required to withhold any funds.
Apply for a Clearance Certificate Early: If you are an Australian resident, it is wise to apply for an ATO Clearance Certificate as soon as you decide to sell. Processing times can vary, so acting early helps prevent potential settlement delays.
Provide the Certificate to the Buyer: Once you receive the certificate, provide a copy to the purchaser or their legal representative well ahead of the settlement date. This gives them the legal certainty required to release the full sale price to you.
Consider Complex Structures: If the property is held in a trust, it is the trustee's residency that is relevant. For co-owned properties, each vendor needs to provide their own certificate. Understanding these details is vital, particularly for arrangements like a bare trust used for property ownership.
Plan for Withholding if You're a Foreign Resident: If you are a foreign resident, withholding is a standard part of the process. You may apply for a variation to reduce the withholding rate if you can demonstrate that your final tax liability will be less than the standard 15%.
By understanding these roles with diligence and foresight, both buyers and sellers can fulfil their responsibilities, paving the way for a transaction that is both compliant and free of last-minute stress.
When dealing with the foreign resident capital gains withholding rules, it is essential to understand two key ATO tools: the Clearance Certificate and the Variation application. Knowing when and how to use these is crucial for ensuring a property sale proceeds smoothly and all financial obligations are met correctly.
For any Australian resident selling a property, the Clearance Certificate provides the most direct path to a clean settlement. It is an official declaration from the ATO confirming your status as an Australian resident for tax purposes. When you provide this to the buyer, their obligation to withhold funds is removed. This allows you to receive the full purchase price on settlement day.
Getting a Clearance Certificate
Applying for a Clearance Certificate is a straightforward process, but it should not be left until the last minute. Proactivity is essential, as ATO processing times can vary.
Here’s how it works:
- Lodge the Application: You or your authorised representative will need to complete the Clearance certificate application for Australian residents online form.
- Ensure Accuracy: It is critical that the name and Tax File Number (TFN) on the application perfectly match the details on the property’s certificate of title. Even a minor discrepancy can lead to delays or rejection.
- Submit It Early: I always advise clients to apply as soon as they list their property for sale. The certificates are valid for 12 months, so there is no disadvantage in acting early.
Consider an Australian professional selling their investment property. The most prudent course of action is to submit the certificate application well before a buyer has been found. This small act of foresight can prevent significant stress and complications as settlement approaches.
When to Use a Variation Application
The Variation application serves a different purpose. It is designed for vendors who are genuine foreign residents for tax purposes but believe the standard withholding rate is too high relative to their actual capital gains tax liability.
This is the tool used to request a reduction in the withholding amount from the ATO. If your application is successful, the ATO will issue a notice to the buyer specifying a lower rate, which could, in some cases, be a nil rate.
A variation does not eliminate your tax obligation. It simply aligns the withholding amount more closely with your final tax liability, which can significantly improve your cash flow from the transaction.
A variation may be appropriate in several situations:
- You Have a High Cost Base: If you paid a substantial amount for the property or have invested heavily in capital improvements, your actual gain might be modest.
- You Have Carry-Forward Capital Losses: You may have capital losses from prior years that can be used to offset the gain from the current sale.
- There is No Gain or a Capital Loss: In some circumstances, a vendor may sell a property for less than its cost base. In this case, withholding any amount would be inappropriate.
Imagine a new migrant to Australia who is still considered a foreign resident for tax purposes. They sell a property they purchased a few years ago in a flat market. After accounting for all costs, their net capital gain is minimal. Applying for a variation allows them to reduce the amount of cash withheld at settlement, ensuring they are not out of pocket while waiting for a tax refund. Assisting clients with this process is a core part of how we build effective tax strategies for Australian investments.
In essence, both the Clearance Certificate and the Variation application are instruments of good financial management. They provide a clear, official process to ensure the correct amount of tax is managed at the right time. Approaching these processes early and with accurate information is a hallmark of disciplined financial planning.
Seeing it in Action: Real-World Scenarios
While understanding the theory is important, seeing how these tax rules apply in practice provides true clarity. Let's walk through a few common scenarios faced by our clients to illustrate how the foreign resident capital gains withholding rules function in different situations.
Every person's circumstances are unique, and these examples highlight the importance of careful planning and tailored advice.
The Medical Professional Selling an Investment Property
Dr. Anya Sharma is a surgeon who has been an Australian resident for tax purposes for many years. She decides to sell an investment property in Sydney to rebalance her portfolio. As the property's value is over the relevant threshold, the FRCGW rules are a key consideration.
Anya understands that a proactive approach is vital for a smooth settlement.
- Her Prudent Action: Well before securing a buyer, Anya applies to the ATO for a clearance certificate. She is careful to ensure her name on the application is an exact match to the name on the property's title deed.
- The Outcome: The ATO issues the certificate, which is valid for 12 months. When a buyer is found, her solicitor provides a copy during the contract exchange.
- The Result: The purchaser has legal confirmation that Anya is an Australian tax resident. Consequently, they are not required to withhold any of the purchase price. Dr. Sharma receives the full settlement amount on schedule, avoiding any unexpected cash flow complications and keeping her financial plans on track.
The Small Business Owner Selling Commercial Premises
Next, consider David Chen, who operates a successful manufacturing business. He is selling a commercial warehouse owned by his company, "Chen Manufacturing Pty Ltd," as part of a business restructure.
David is aware that the foreign resident capital gains withholding rules apply to commercial property just as they do to residential property. As the vendor is a company, its residency status is the determining factor.
The type of property or the nature of the owner—be it a company, a trust, or an individual—does not change the fundamental obligation. The purchaser is legally required to withhold funds unless the vendor provides a valid exemption.
- His Prudent Action: David's company applies for an ATO clearance certificate under its ABN. Just as with an individual, the legal name on the certificate must perfectly match the owner registered on the title.
- The Outcome: The buyer's conveyancer verifies the clearance certificate against the property title. As all details align, "Chen Manufacturing Pty Ltd" is confirmed as an Australian resident entity, so the transaction can proceed without withholding.
- The Result: The sale settles without issue. David receives the full proceeds promptly, allowing him to reinvest the capital into his new business strategy without delay.
The New Migrant Navigating Residency Rules
Finally, let's look at Sofia Rossi. She moved to Australia from Italy two years ago on a temporary skills visa. While she lives and works in Melbourne, for tax purposes, she may still be considered a foreign resident. Sofia decides to sell a small apartment she purchased upon her arrival.
Her visa status complicates matters, and obtaining a clearance certificate may not be an option. The rules for buying property on a temporary visa can be complex, and selling adds another layer of compliance.
- The Challenge: Without a clearance certificate, the buyer is legally obligated to withhold 15% of the sale price. However, Sofia’s actual capital gain is quite small after factoring in her purchase price and other costs. The standard withholding amount would far exceed her final tax liability.
- Her Prudent Action: Working with her adviser, Sofia applies to the ATO for a variation. She provides detailed calculations—including the property's cost base and her estimated capital gain—to demonstrate that the 15% rate is excessive in her circumstances.
- The Outcome: The ATO reviews her application and agrees. They issue a variation notice directly to the buyer, instructing them to withhold a much smaller, more appropriate amount that reflects her likely tax liability.
- The Result: While some funds are still withheld, the amount is fair and reasonable. This makes a significant difference to her financial position at settlement, freeing up her capital rather than having it held by the ATO for months until her tax return is lodged.
These examples show that whether you need a clearance certificate or a variation, understanding the foreign resident capital gains withholding process is vital for protecting your financial outcome.
Final Thoughts: A Proactive Approach to FRCGW
Navigating the Foreign Resident Capital Gains Withholding rules is more than a compliance exercise; it is a critical component of responsible financial management during a property transaction. A misstep can lead to costly penalties and frustrating delays, but with foresight and careful planning, you can maintain control of the process.
The key is to be proactive. The official ATO processes, such as clearance certificates and variations, should be viewed as tools designed to facilitate a fair and orderly transaction. By engaging with these processes early, you are taking disciplined action to prevent last-minute issues from disrupting your settlement. Wise decisions come from understanding your responsibilities as well as the potential benefits.
True financial stewardship is not just about identifying opportunities—it is about understanding and managing obligations. FRCGW is a perfect example where careful preparation directly protects your financial outcome.
While this guide provides a framework, it is not a substitute for professional advice tailored to your unique circumstances. Combining this knowledge with expert guidance is the foundation for building smart investment tax strategies for Australian investors.
The Takeaway: Approaching your FRCGW obligations with diligence and foresight is the most reliable path to a smooth transaction. This disciplined approach will leave you with a clear understanding of the process and the quiet confidence that comes from managing your financial affairs effectively.
Common Questions on Foreign Resident Capital Gains Withholding (FRCGW)
Property transactions often raise specific questions about tax compliance. To provide further clarity, we have compiled answers to some of the most common queries we receive regarding the foreign resident capital gains withholding rules. Our aim is to help both buyers and sellers proceed with confidence.
What Happens if the Withholding Amount Is More Than My Actual Tax Bill?
This is a common concern for foreign resident sellers. If the amount withheld is greater than your actual tax liability, you are entitled to a refund.
The withheld amount is treated as a pre-payment towards your tax obligation. When you lodge your Australian income tax return for that financial year, you will declare the capital gain from the sale and claim a credit for the amount that was withheld. If the tax you owe is less than the amount paid to the ATO, your assessment will result in a refund of the difference.
Does FRCGW Apply to Inherited Properties?
Yes, it may apply. If a foreign resident beneficiary inherits an Australian property and subsequently sells it, the FRCGW rules could be triggered.
The determining factor is always the seller's residency status for tax purposes at the time the sale contract is executed. If the beneficiary selling the property is a foreign resident, the purchaser is obligated to withhold the tax, unless the seller obtains a variation from the ATO. The calculation of capital gains on inherited property involves its own complex rules, so seeking personal advice in these circumstances is highly recommended.
How Do the Latest Rule Changes Affect Me?
The FRCGW rules are not static, and awareness of recent changes is part of sound financial management. The regime was significantly amended on 1 January 2025, with the changes expanding its reach considerably.
The withholding rate increased to 15%. However, the most significant change was the removal of the $750,000 property value threshold. This means the 15% withholding now applies to all sales by foreign residents, irrespective of the property's value. You can read more about these fundamental changes to the FRCGW rules here.
Can I Get an Extension if I Can’t Get a Clearance Certificate in Time?
No. The ATO is very strict on this point and does not grant extensions for providing a clearance certificate. The certificate must be provided to the purchaser on or before the day of settlement.
If a valid clearance certificate is not available at settlement, the purchaser is legally required to withhold the funds and remit them to the ATO. This is why it is critical for Australian resident sellers to apply for their certificate as early as possible in the sale process.
This firm deadline underscores why a proactive approach is necessary. Leaving the application to the last minute creates a significant risk of cash flow issues at a critical time. A little careful planning can go a long way towards ensuring a smooth settlement.
At Everglow Prosperity, we provide clear, integrated guidance to help you manage your tax and advisory needs. To discuss how these rules impact your specific situation, connect with our team today. https://everglow.au
Article created using Outrank
 English
 Chinese (Hong Kong)
 Chinese (China)
 Greek
 Hebrew
 Vietnamese
 Arabic
