
A buyer in Sydney offers more than you expected for the property, and the emotional arc changes fast. Relief turns into a sharper question. What does this mean for tax, cash flow, and the next stage of life?
For property owners, investors, and families, capital gains tax on property in Australia is rarely just a calculation. It may affect whether you sell now or later, whether you keep a former home as a rental, and how much liquidity you carry into the next decision. For a plain-English overview of how capital gains tax affects property, it helps to start with the practical question first, then move into the rules.
Capital Gains Tax Property Australia
By Panbo Ye, CFP® | FCPA | SSA® | Founder, Everglow
Who this article is for: Property owners, investors, professionals, and families weighing a sale, a move, or a restructure and needing a clear view of property CGT consequences.
If you've bought, held, rented, or lived in Australian property, capital gains tax may apply when you dispose of it, but the outcome depends heavily on the facts. Residency, ownership period, whether it was your home, and how the property was used all matter. If you're also comparing acquisition costs with sale outcomes, it's worth understanding related state-based transaction costs such as property stamp duty considerations.
Table of Contents
- Introduction
- Understanding Capital Gains Tax on Property
- How to Calculate CGT on a Property Sale
- Can You Avoid CGT on Your Home Sale
- Special CGT Rules for Different Circumstances
- Reporting and Paying Your Property CGT
- Frequently Asked Questions About Property CGT
- Does CGT apply if I demolish my home and rebuild?
- Does CGT apply to vacant land?
- What if I rented out only part of my home?
- Do major renovations affect my cost base?
- What if the property sells for more than the foreign resident withholding threshold and I am an Australian resident?
- Can I rely on broad online CGT calculators?
Introduction
A strong offer can make a sale look simple. Then the tax question lands, especially if the property has shifted roles over time from home, to rental, to family asset, or to part of a broader wealth plan.
In practice, capital gains tax property Australia issues sit right at the intersection of tax, family planning, migration status, and timing. Capital Gains Tax (CGT) is a tax on the profit made on disposal of an asset, but for property owners the core issue isn't the label. It's whether the gain is fully exempt, partly exempt, discounted, or fully assessable in the year of sale.
For professionals such as Dr Anya Sharma, or new migrants such as Wei, or families using trusts, the same sale can produce very different tax outcomes. That's why a property decision should be tested before the contract is signed, not after.
Practical rule: The right CGT question isn't “Will I pay tax?” It's “What part of this gain is taxable, in whose hands, and in which financial year?”
- Life stage matters: A move for work, school catchment, retirement, or migration can change the CGT position.
- Structure matters: Individual ownership, trusts, and superannuation don't produce the same result.
- Timing matters: The contract date and ownership period can materially change the treatment.
The core answer is simple. Property CGT may apply to the gain on sale, but the amount depends on your facts, not the headline price.
Understanding Capital Gains Tax on Property
A surgeon relocates interstate, keeps the former home as a rental for several years, then sells to free up cash for a larger family home. A new migrant buys after becoming an Australian tax resident and assumes the tax outcome will be simple. A family trust disposes of a long-held property during a succession plan. Each sale can produce a different CGT result, even where the gain looks similar on paper.
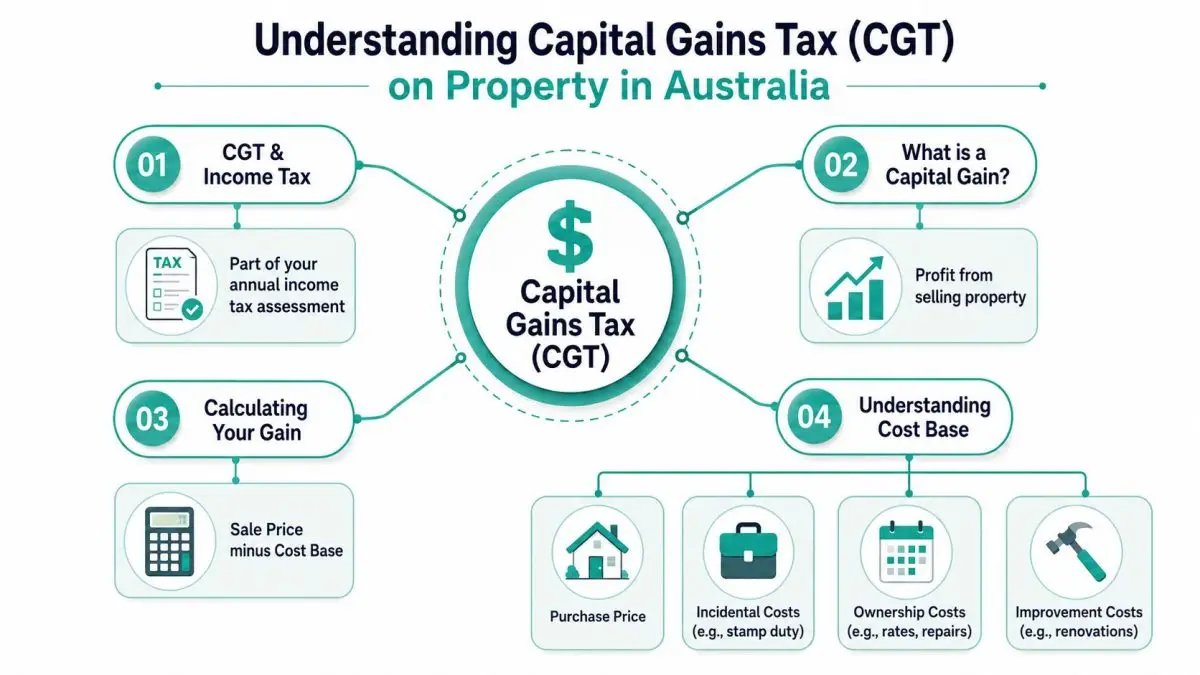
Capital gains tax on property sits inside the income tax system. The gain is not taxed as a separate property levy. It is worked out under the CGT rules, then included in the tax position of the relevant owner for the year of the CGT event. For property, that usually means the contract date drives the income year, which matters if a sale lands alongside a bonus, business income, or a retirement event.
The basic framework has been in place since Capital Gains Tax was introduced in Australia on 20 September 1985, with pre-CGT assets generally outside the regime. Current as at 07/2026. Old ownership dates still matter, particularly for families dealing with inherited property or long-held assets that have moved through different uses over time.
What the gain actually represents
The starting point is simple. CGT applies to the capital gain, not the full sale price.
That distinction is where errors begin. Even experienced clients often remember the purchase price and sale price but overlook the tax treatment of stamp duty, legal fees, selling costs, capital improvements, and periods where holding costs may or may not form part of the cost base. A proper review also has to separate deductible revenue expenses from capital amounts. For investors who want the broader context around ownership and sale issues, this investment property tax guidance is a useful companion.
Two concepts do most of the technical work:
- Cost base: the amounts the tax law allows you to count toward the property's CGT cost.
- Capital proceeds: the amount received, or taken to be received, on disposal.
That sounds mechanical, but the primary advisory work is classification. Was the property ever your main residence? Was part of it used to produce income? Was ownership held personally, jointly, through a trust, or after migration? Those facts change the taxable portion before any discount is considered.
The 12-month holding rule
For Australian resident individuals and trusts, a capital gain on property held for at least 12 months may qualify for the CGT discount under the ATO's CGT discount rules. Current as at 07/2026. In broad terms, that can reduce the discountable gain by 50% for eligible individuals and by 33 1/3% for eligible complying super funds. Companies do not get the discount.
This is one of the most commercially important timing rules in property tax. A sale exchanged a few weeks too early can produce a materially higher tax bill. A delayed sale, on the other hand, may improve the CGT outcome but create holding costs, market risk, or cash flow pressure. The right answer depends on the numbers and the life event driving the sale.
I often see three groups miss the practical point here. Professionals relocating for work focus on the purchase of the next home and leave the old property's CGT history unchecked. New migrants may not realise that residency status affects discount access and other CGT outcomes. Families using trusts or multiple owners sometimes assume the gain will be shared or discounted in the way they expect, only to find the structure itself changes the result.
For readers comparing approaches across jurisdictions, the 2026 UK capital gains tax guide shows how heavily outcomes can turn on residence rules, valuation evidence, and ownership history. The Australian lesson is the same. Good CGT planning starts well before listing the property.
Property CGT is rarely just a maths exercise. It is part of a larger decision about timing, residency, family structure, and what the sale is meant to fund next.
How to Calculate CGT on a Property Sale
For Australian tax residents, the working formula is straightforward in principle. The net capital gain is calculated from capital proceeds less the cost base, and if the property was held for at least 12 months, the gross gain may then be reduced by 50% before being added to taxable income and taxed at the marginal rate. Current as at 07/2026.
The hard part isn't the formula. It's assembling the right facts and using the right ownership history.
Worked example for Wei in Parramatta
Wei is a new Sydney migrant professional. He bought an investment apartment in Parramatta after becoming an Australian tax resident and has held it for more than 12 months. He now wants to sell because his family is planning a home purchase and needs clarity on after-tax cash.
Below is a simple worked example using one set of numbers to show the mechanics.
This table shows the worked example for Wei's Parramatta investment apartment.
| Item | Amount (AUD) |
|---|---|
| Purchase price | $700,000 |
| Stamp duty | $25,000 |
| Legal fees on purchase | $2,000 |
| Capital improvement costs | $20,000 |
| Cost base | $747,000 |
| Sale price | $980,000 |
| Agent commission and selling legal fees | $18,000 |
| Capital proceeds | $962,000 |
| Gross capital gain | $215,000 |
| 50% discount | $107,500 |
| Net capital gain added to taxable income | $107,500 |
What this means in practice
Wei doesn't pay tax on the sale price. He adds the net capital gain to his taxable income for the financial year. If his other income already places him in a high marginal bracket, the cash set aside for tax may need to be substantial.
That last point catches people out. The accounting gain and the tax cash requirement aren't the same thing as available sale proceeds after debt reduction, legal fees, and next-home costs.
- Step one: Confirm the ownership entity and residency status for the whole ownership period.
- Step two: Rebuild the cost base from records, not memory.
- Step three: Separate capital improvements from expenses already claimed elsewhere.
- Step four: Test whether any exemption or discount changes the position.
A spreadsheet can do the arithmetic. It can't decide whether a period of occupancy counts as main residence use, or whether a cost belongs in the cost base.
If you're comparing Australian treatment with overseas frameworks because you hold assets in more than one country, a valuation-focused piece such as this 2026 UK capital gains tax guide can be useful for contrast, but the Australian result must be worked from Australian rules and residency facts.
What works and what doesn't
Good CGT planning usually looks ordinary. You keep records, identify the contract timing early, and review the ownership story before listing the property.
What doesn't work is trying to reconstruct years of costs after exchange, or assuming every renovation, holding cost, or family arrangement automatically helps. It may not.
For most sales, the decisive work happens before the property hits the market. Once the contract is signed, your planning room narrows sharply.
Can You Avoid CGT on Your Home Sale
Sometimes yes. Often partly. Occasionally not at all.
The main residence exemption is the most important relief in property CGT, but it's also where oversimplified advice causes problems. A property can feel like “the family home” and still produce a partial CGT issue if it was rented, used to earn income, or ceased to be the chosen main residence for part of the ownership period.
When the home sale may be exempt
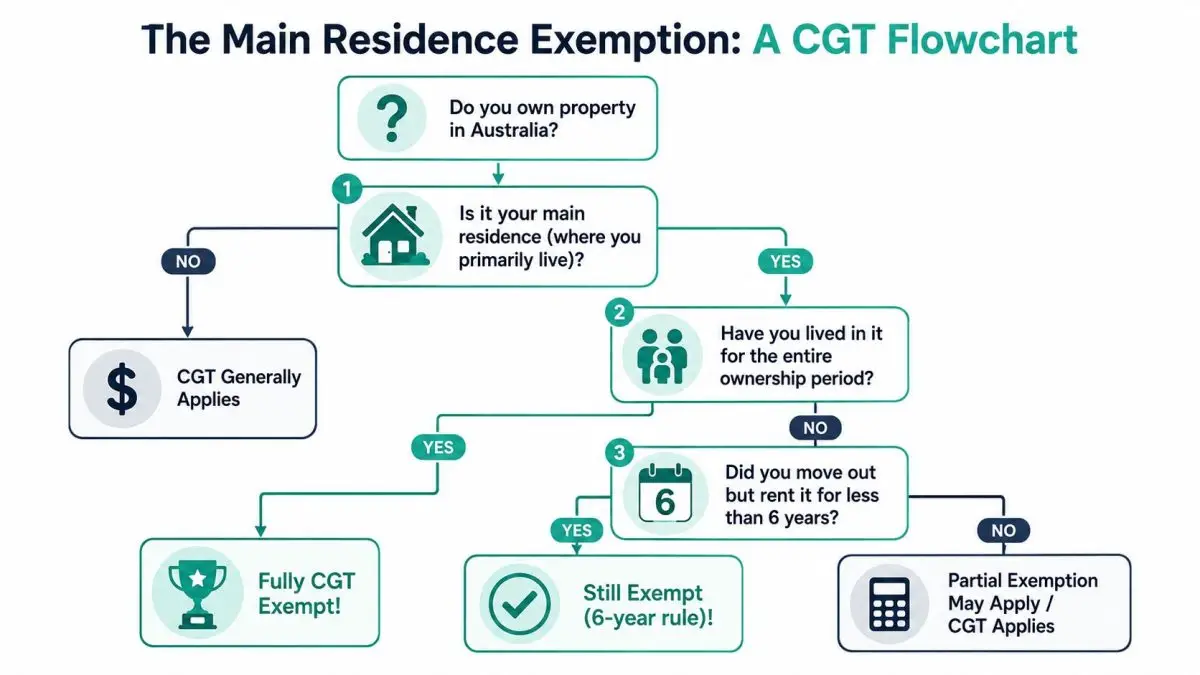
If the dwelling was your main residence throughout ownership and wasn't used in a way that alters the exemption, a full exemption may be available. The broad principle is familiar. The detail is where mistakes happen.
For Tom, a Brisbane tradie, that issue might arise if he ran part of his business from home. For Dr Anya Sharma, it may arise if she moved for work and rented the home while keeping options open.
How the 6-year rule actually works
That sounds simple, but the application isn't automatic. The property must have been validly established as the main residence before the absence. The rule also needs care where people move back in, then out again, or where family circumstances create overlapping claims. If this issue is central to your decision, a more specific review of the main residence exemption and 6-year rule can help frame the right questions.
Main residence planning succeeds when the timeline is documented clearly. Dates of occupation, vacancy, rental use, and any second property election should be recorded early.
Partial exemption scenarios
A full exemption may not be available where:
- Part of the home earned income: Renting a room or using part of the dwelling in a way that changes the private-use profile may affect the result.
- The home wasn't your main residence for the full period: A move-in delay or later conversion to investment use can matter.
- Multiple properties are involved: You generally can't treat more than one property as your main residence for the same period, subject to specific rules.
One of the most common errors is assuming that moving back into a property “resets everything”. Sometimes it helps. Sometimes it only affects a later period.
The primary question isn't whether the home was ever your residence. It's whether the exemption applies across the exact ownership timeline and actual use of the property.
Special CGT Rules for Different Circumstances
A surgeon takes a role in Singapore, keeps the Melbourne apartment for a few years, then sells after returning to Australia. A newly arrived family buys a home in one spouse's name, later shifts an investment property into a trust, and assumes the tax result will sort itself out at sale. An executor holds the family home while siblings argue about timing. These are all property decisions, but they are also life-stage decisions, and CGT often becomes the point where poor structuring and weak records turn into real cost.
Inherited property
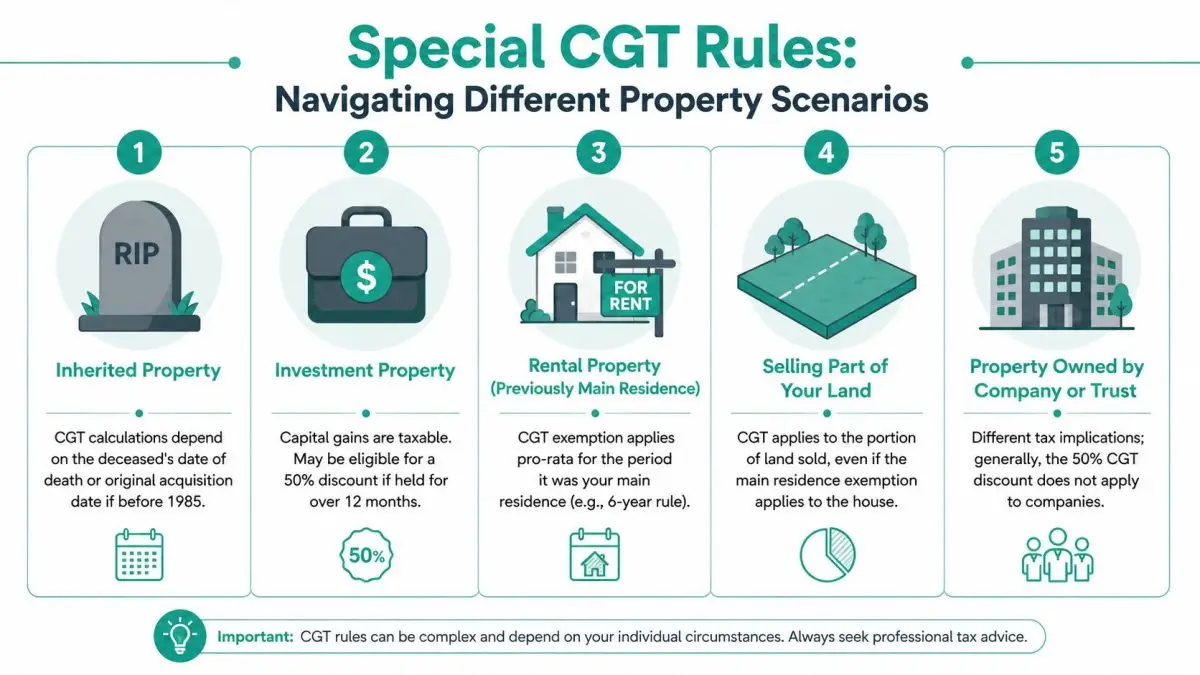
Inherited dwellings follow their own CGT rules, and timing often drives the outcome. The ATO explains that a main residence exemption may still be available where inherited property is sold within two years of death and the relevant conditions are met, including rules about income-producing use.
In practice, executors and beneficiaries need more than a rough understanding of the exemption. They need a clear file on who lived in the property, whether it was rented, when probate delays arose, and why the sale occurred when it did. Families with blended family issues, multiple beneficiaries, or estate assets held alongside trusts can lose the benefit of an otherwise available exemption by drifting past key dates or changing the property's use without advice.
Foreign residents and new migrants
Residency is not a side issue. It affects access to the CGT discount, the main residence rules, and in some cases whether a property sale creates a cash flow problem at settlement.
For new migrants, the starting point is usually the acquisition date, residency status across the ownership period, and whether the property was held before becoming an Australian tax resident. For Australians leaving the country, the analysis often shifts to whether they became a foreign resident for tax purposes and what that means for any later sale. These are technical questions, but they sit inside practical decisions about career moves, school choices, and where the family will live.
There is also a settlement issue. Under the ATO's foreign resident capital gains withholding rules, buyers generally must withhold an amount from certain property sales unless the seller provides a valid clearance certificate or variation applies. That withholding is not the final tax. It is a collection mechanism. Even so, it can materially reduce sale proceeds available on settlement day, which matters if the funds are needed for a replacement purchase or debt repayment.
Trusts and SMSF ownership
Property held through a trust or SMSF needs to be reviewed as part of the broader family balance sheet, not just the tax return for the year of sale.
A discretionary trust can support asset protection and succession planning, but it changes who makes the gain, who may receive distributions, and how records need to be kept over time. An SMSF sits in a different tax environment again, with separate compliance rules around acquisition, use of fund assets, related party dealings, and retirement phase planning. Those structures can be effective. They also reduce flexibility if they are set up for the wrong reason or funded the wrong way.
Changing ownership is often where clients create an avoidable CGT event. Anyone considering a transfer should examine duty, CGT, financing, land tax, and control together before signing anything. A guide on transferring property into a trust can help frame the issues, but the main question is whether the structure still suits the family's next stage. The same caution applies to a Self-Managed Super Fund (SMSF).
- Estates: check the date of death, use of the property after death, and whether delays can be evidenced.
- Professionals working overseas or interstate: confirm tax residency before listing the property and deal with withholding requirements early.
- New migrants: identify which assets are already within the Australian CGT net and keep records from the date residency begins.
- Families using trusts or SMSFs: review the structure before any transfer, refinance, or sale, not after contracts are signed.
CGT on property changes sharply once ownership, residency, or family structure becomes more complex. The tax calculation is only one part of the decision. The better result usually comes from planning before the event, while there is still time to choose the right owner, the right timing, and the right evidence.
Reporting and Paying Your Property CGT
A common mistake looks harmless at first. A family signs a contract in June, settlement lands in August, and they assume the tax issue belongs to the next financial year. It usually does not. For CGT purposes, the key date is generally the contract date, and that timing can affect cash flow, instalments, residency treatment, and which return must carry the gain.

That distinction matters more than clients expect. A surgeon selling a former home after years of interstate work, a new migrant disposing of an asset after becoming an Australian resident, or parents selling property through a trust can all face very different reporting outcomes from the same sale price. The tax return only shows the final number. The actual work involves making sure the ownership history, residency status, and cost base records support that number.
If the property was held for at least 12 months, individuals and trusts may be entitled to the CGT discount, subject to the usual rules. If it was held for less than 12 months, the gain is generally assessed without that discount. In either case, the gain or loss is usually reported in the tax return for the year in which the contract was signed.
What to do before and after exchange
The cleanest file is prepared before settlement, not after it.
- Before exchange: confirm the legal owner, review the contract date you are working toward, check residency status, and determine whether a clearance certificate or withholding process applies.
- After exchange: prepare the CGT calculation for the correct income year, including any apportionment, discount treatment, and prior-year capital losses.
- Before lodgment: match the return to the file. That includes purchase documents, improvement costs, selling expenses, depreciation history, and any advice relied on for main residence or trust treatment.
Sellers who may be affected at settlement should review the rules on foreign resident capital gains withholding early. If ongoing tax support is needed around the sale year, this is also the point where customized tax and accounting services become practically useful.
Settlement is when funds change hands. The reporting year is usually fixed earlier.
The practical rule is simple. Get the tax position settled before exchange, because by the time the contract is signed, the reporting year and any withholding consequences may already be locked in.
Frequently Asked Questions About Property CGT
A property sale often lands in the middle of a bigger decision. A surgeon starts consulting from home, a family rebuilds after outgrowing the house, or a new migrant sells land bought before arriving in Australia. In each case, CGT turns on the facts around use, timing, ownership, and records, not just the sale price.
Does CGT apply if I demolish my home and rebuild?
Sometimes. Demolition does not automatically cancel main residence treatment, but it does put pressure on the timeline and the evidence.
A key question is whether the property still qualifies for the exemption during the periods before construction, during the rebuild, and after you move back in. If the property was rented, left vacant for too long, or held through a structure that changes the analysis, part of the gain may become taxable. Families who rebuild after a life-stage change often assume the exemption continues without interruption. That assumption needs to be tested.
Does CGT apply to vacant land?
Usually, yes. Vacant land sits within the CGT regime unless a specific exemption applies, and in many cases none does.
This catches owners who plan to build later, subdivide, or hold land for family use without ever establishing a qualifying main residence position. New migrants should be especially careful here, because the tax outcome may depend on when Australian tax residency began and whether the land was acquired before that point. Records for acquisition costs, holding costs where relevant, and development expenses matter more than many owners expect.
What if I rented out only part of my home?
That usually leads to a partial exemption rather than a full one. The taxable portion is commonly affected by the floor area used to produce income and the period of that use.
This issue comes up often with professionals who see clients from home, families who lease a room, and owners who convert part of the house into a separate studio. The tax effect is rarely dramatic in the early years, which is why it is often ignored. The problem appears later, when no one can clearly reconstruct when the arrangement started or how much of the property was set aside for income-producing use.
Do major renovations affect my cost base?
Yes, if the expenditure is capital in nature and properly documented. Major works can increase the cost base, which may reduce the eventual capital gain.
The line between repairs and improvements matters. So does prior tax treatment. If an amount has already been claimed as a deduction, or reflected through depreciation or capital works treatment, it cannot be added again to the CGT calculation. For families renovating over many years, and for owners improving a property before sale, invoices and contractor records often determine how much value can be recognised.
What if the property sells for more than the foreign resident withholding threshold and I am an Australian resident?
Resident sellers still need to deal with the clearance certificate process. If the certificate is not in place by settlement, the buyer may be required to withhold part of the price even though the seller is an Australian resident.
This is an administrative issue, but it affects cash flow in a real way. I have seen it disrupt sale proceeds for professionals changing cities and for families relying on the full settlement amount to complete their next purchase. As noted earlier, the paperwork should be handled before exchange wherever possible.
Can I rely on broad online CGT calculators?
Only for a rough estimate. They can be useful for a clean fact pattern, but many property files are not clean.
Calculators usually miss the issues that change the answer. Partial main residence use, residency changes, inherited property, trust ownership, deceased estate timing, and prior capital losses all require judgement as well as arithmetic. For astute owners, CGT is often part of a broader decision about timing a sale, funding the next property, or restructuring family assets. A calculator cannot do that analysis.
Property CGT is easier to manage when the ownership history is clear, the records are complete, and the tax position is reviewed before the sale is locked in. For many owners, the hard part is not the formula. It is understanding which parts of the property story the law will count.
If you would like clarity on how these principles may apply to your own circumstances, contact Everglow on 1300 913 929 or email contact@everglow.au.
To book directly: Book a meeting with Panbo.
For broader support across tax, structuring, wealth, lending, and advisory, visit Everglow Prosperity.
 English
 Chinese (Hong Kong)
 Chinese (China)
 Greek
 Hebrew
 Vietnamese
 Arabic
