

For many Australians, establishing a self-managed super fund (SMSF) represents a considered move toward greater involvement in their financial future. It is a shift from being a member of a large fund to becoming a trustee, responsible for steering your own retirement assets. This structure places the day-to-day investment and strategic decisions in your hands, offering a level of direct oversight not available elsewhere.
What is a self managed super fund?
Before exploring the potential benefits, it is important to understand what an SMSF is. It is not merely another superannuation account; it is your own private superannuation trust, established and administered by you and up to five other members, in accordance with Australian law.
As trustees, you are personally responsible for all aspects of the fund, from selecting investments to ensuring compliance with Australia's superannuation and tax legislation. This represents a fundamental change from being a passive member to an active director of your financial journey.
The responsibilities of a trustee
Assuming the role of a trustee is a significant legal commitment, overseen by regulators such as the Australian Taxation Office (ATO) and ASIC. The core duties are clearly defined and include:
- Acting in the best financial interests of all members of the fund.
- Formulating and regularly reviewing a compliant investment strategy.
- Maintaining detailed records of all decisions, transactions, and trustee meetings.
- Arranging an annual audit by an approved, independent SMSF auditor.
This hands-on approach is often what attracts Australian professionals and business owners to SMSFs. The desire for greater control has contributed to significant growth in the sector, with over 661,000 SMSFs managing more than $1 trillion in assets as of September 2025, according to APRA data. This represents approximately a quarter of Australia’s total superannuation pool.
Understanding the self-managed super fund rules is an essential first step. This path may offer greater autonomy, but it requires discipline and careful stewardship in return.
Gaining control over your investment strategy
A primary reason individuals consider an SMSF is the direct control it provides over investment decisions. As a trustee, you have the ability to construct a portfolio that reflects your financial objectives, risk tolerance, and personal values. This flexibility may open access to a broader range of asset classes that are often unavailable in standard superannuation funds.
With an SMSF, and subject to superannuation laws, it may be possible to invest directly in residential or commercial property, shares in unlisted companies, or even specific collectibles, provided each investment is consistent with the fund's documented investment strategy. This can allow for strategic alignment between your personal, business, and retirement wealth.
A practical example for business owners
Consider Dr. Alana, a medical specialist operating her own practice. She found the investment options in her industry super fund did not align with her specific circumstances.
By establishing an SMSF with her partner, Dr. Alana could explore purchasing the commercial premises from which her clinic operates. This strategy would typically involve a Limited Recourse Borrowing Arrangement (LRBA) and must satisfy strict criteria from both the ATO and lenders.
Under this arrangement, her clinic would pay commercial rent directly to the SMSF, which contributes to her retirement savings while providing her business with long-term tenancy security. It is an example of how the benefit of a self managed super fund may create synergy between business and retirement goals.
A core principle of superannuation law is that every investment must be made for the sole purpose of providing retirement benefits to the fund's members. All decisions must be commercially sound and meticulously documented.
Alongside the property, Dr. Alana's SMSF investment strategy also includes a portfolio of Australian shares selected for their dividend yields and potential franking credits, a level of strategic integration not possible in her previous fund. For those considering a similar path, our specialised advisory services may help provide clarity.
A broader investment universe
The freedom to choose specific assets is a significant factor for many Australians. According to APRA's superannuation statistics and findings, SMSFs held over $1 trillion in assets by September 2025. These funds have substantial holdings in listed shares (28%) and cash (16%), reflecting trustees' ability to adjust strategies in response to market conditions.
The following table provides a general comparison of investment options.
Comparing investment options: SMSF vs. standard super funds
This table compares typical investment options, highlighting the expanded flexibility an SMSF may offer.
| Asset Class | Availability in SMSF | Typical Availability in Industry/Retail Funds |
|---|---|---|
| Direct Property (Residential/Commercial) | Yes, subject to strict rules (e.g., LRBAs) | Generally no |
| Direct Australian/International Shares | Yes, full choice of individual companies | Limited to a curated list or managed funds |
| Cash and Term Deposits | Yes, from any Authorised Deposit-taking Institution | Limited to the fund's chosen providers |
| Unlisted Shares / Private Equity | Yes, with careful due diligence and valuation | Very rare, usually via specialised fund options |
| Collectibles (e.g., Art, Precious Metals) | Yes, with extremely strict storage and insurance rules | No |
| Managed Funds and ETFs | Yes, from any provider | Limited to an approved menu of options |
| Business Real Property (Own Premises) | A common and powerful strategy for business owners | No |
This expanded universe is a key attraction, but it is matched by a profound responsibility. Every investment requires appropriate due diligence and must be managed prudently.
Strategic tax planning opportunities
An SMSF may provide greater scope for strategic tax planning. While all Australian superannuation funds operate in a concessionally taxed environment, an SMSF allows trustees a degree of control over tax outcomes that is generally not available in large public funds. This is not about seeking loopholes but about thoughtful, long-term planning based on established tax laws.
Tax in the accumulation phase
While you are working and contributing to your super, your SMSF is in the accumulation phase. During this time, the fund's investment earnings, such as rent or dividends, are generally taxed at a concessional rate of 15%. For many professionals, this rate is significantly lower than their personal marginal tax rates.
Furthermore, if the fund sells an asset held for more than 12 months, any capital gain may be eligible for a one-third discount, which can reduce the effective capital gains tax (CGT) rate to 10%. The ability as trustee to determine the timing of asset sales allows for careful management of these tax events.
Tax in the retirement phase
The tax environment can change significantly when a member moves into the retirement phase and begins drawing a pension. Subject to certain limits, the investment earnings and capital gains generated by assets supporting that pension are generally tax-free.
Once a retirement income stream commences, earnings from the assets supporting it may be taxed at 0%. This is subject to the transfer balance cap, a lifetime limit on the amount of super that can be transferred into this tax-free retirement phase.
This can create significant planning opportunities. For instance, a trustee might strategically time the sale of a major asset, such as an investment property, to occur after the fund has moved into the retirement phase, potentially reducing the capital gains tax liability on that sale.
Estate planning with an SMSF
Beyond investment and tax, an SMSF can be a valuable tool for estate planning. It provides a framework for creating a clear and legally robust plan for your legacy, offering a level of certainty that may be difficult to achieve in larger super funds. This is a matter of good stewardship—ensuring the wealth you have built is passed on according to your wishes, which can minimise ambiguity for your family.
Directives for your dependants
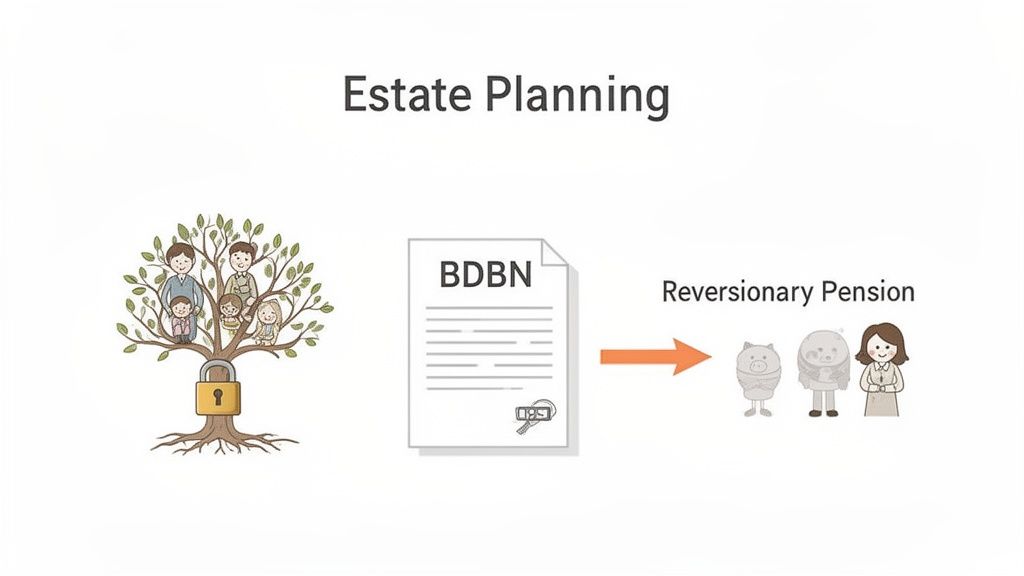
A cornerstone of SMSF estate planning is the Binding Death Benefit Nomination (BDBN). This is a formal, written instruction to the fund's remaining trustees that specifies how your superannuation balance should be distributed to your eligible dependants.
While many large funds offer BDBNs that may lapse every three years, an SMSF's trust deed can be structured to permit a non-lapsing BDBN. This remains valid indefinitely unless you choose to revoke or amend it, providing long-term certainty.
Another powerful option is a reversionary pension. If you are receiving an income stream from your SMSF, you can nominate a dependant—often a spouse—to automatically continue receiving that pension upon your death. This can ensure a seamless transfer of income at a difficult time.
An SMSF allows you to build a legacy framework that can be tailored to your unique family circumstances, helping to minimise the potential for disputes.
Navigating complex family structures
These tools are particularly useful for those with blended families or more complex wishes. For example, a business owner with adult children from a first marriage and a younger child with his current spouse might wish to provide for everyone.
With professional advice, he could establish a reversionary pension for his spouse to ensure her financial security, while a BDBN could direct that any remaining capital be distributed among all three children upon her passing. This kind of tailored planning is a distinct feature of an SMSF. An SMSF is one part of a comprehensive estate plan, which should also include foundational documents like a valid Will.
Understanding the risks and responsibilities
The control offered by an SMSF is balanced by significant legal and administrative responsibilities. As a trustee, you are personally accountable for managing the fund in compliance with Australian law. This includes acting in the best financial interests of all members, maintaining meticulous records, and ensuring every decision aligns with the fund’s sole purpose: providing retirement benefits.
Key compliance obligations include lodging an annual return, arranging an independent annual audit, valuing assets at market value, and adhering to a documented investment strategy. The penalties for non-compliance can be substantial, reinforcing the serious nature of the trustee role. Trustees must also navigate investment risks and commit the necessary time to administration. The benefit of a self managed super fund is best realised by those who embrace these duties and understand when to seek professional guidance.
Practical next steps
Making a decision about establishing an SMSF requires calm and thoughtful consideration. It is a significant financial commitment that demands your time, diligence, and a willingness to understand the details. Before proceeding, it is wise to assess whether you have the capacity for the administrative and investment management duties involved.
A thorough cost-benefit analysis against your current superannuation arrangement is a vital part of responsible financial stewardship. It is also important to consider how an SMSF fits within your broader financial plan. The right choice is one that is well-researched, clearly understood, and supported by professional advice tailored to your specific circumstances. To discuss whether this path is appropriate for you, you may wish to contact us to arrange a meeting.
A concise takeaway
A self-managed super fund offers a high degree of control over your retirement savings, with potential benefits in investment flexibility, tax strategy, and estate planning. However, this autonomy comes with significant legal and administrative responsibilities. The decision to establish an SMSF should be made with a clear understanding of these duties and ideally with the support of qualified professional advice to ensure it aligns with your long-term financial objectives.
If you would like clarity on how these principles may apply to your own circumstances, you may wish to speak with a qualified adviser. You can contact Everglow on 1300 913 929 or email contact@everglow.au to arrange a discussion.
General Advice Warning: The information provided is general in nature and does not take into account your personal objectives, financial situation, or needs. You should seek personal advice before acting on this information.
Want help applying this to your situation?
Every situation is different. Book a time with our team to talk it through, or call us on 1300 913 929.